Bookkeeping for Real Estate Investors: 9 Essential Practices for Better Financial Control
Table Of Contents
Toggle
A rental property can be performing well on paper and still leave its owner with a surprisingly unclear picture of the finances.
It usually starts innocently enough. Rent comes in, bills get paid, and receipts are saved somewhere for later. Then another property is added. There is a second mortgage, another bank account, a new property manager, and a growing list of contractors. Before long, answering a simple question—How did this particular property actually perform last quarter?—takes more work than it should.
That is where bookkeeping for real estate investors earns its value. Good books do more than keep transactions in order. They show where money is coming from, where it is going, and what is happening at each property, giving investors a clearer financial view as their portfolio grows.
Real estate often creates transactions that need context.
Some real estate transactions are easy to record. A plumber’s invoice, for example, usually has an obvious place in the books. Mortgage payments need a little more attention because they may include both principal and interest. The same goes for money received from tenants—it could be monthly rent or a security deposit. Even contractor costs need context, as routine repairs and major property improvements may need to be recorded differently.
Now multiply that across several rentals or entities.
Well-kept books preserve that detail. They also make financial reporting more useful and give accountants and tax professionals cleaner records.
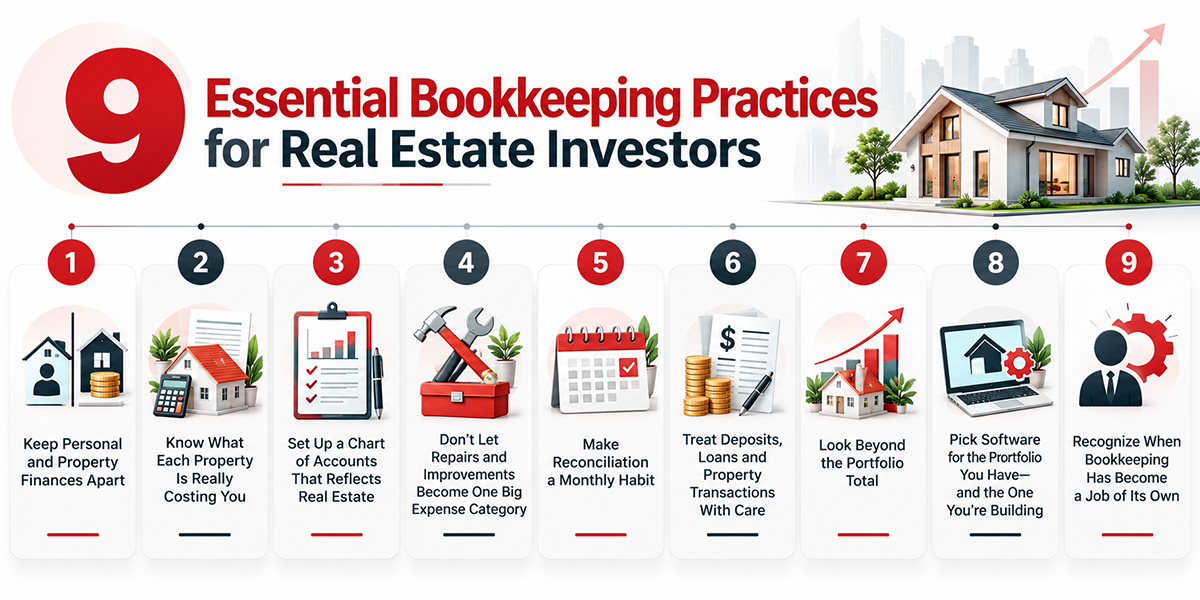
Using the same account for household spending and rental-property expenses may seem harmless when there are only a handful of transactions. It becomes far less convenient when you have to sort hundreds of entries later.
This is a fairly basic part of real estate investor bookkeeping, but getting it right makes almost everything that follows easier.
Bookkeeping for rental properties works better when you can trace income and expenses back to individual properties. Rent, insurance, repairs, maintenance, utilities, and management fees are a few obvious examples.
The point is not to create an exhausting level of detail. It is to retain enough information to answer practical questions about each rental without rebuilding the numbers manually.
That property-level view becomes more valuable as the portfolio grows.
Rental income should be easy to identify. Maintenance, insurance, property management costs, utilities, and other recurring expenses should be easy to identify. Depending on the portfolio, you may also need accounts for deposits, mortgage interest, fixed assets, and other real-estate-specific activity.
More categories are not necessarily better. An overly detailed chart of accounts can become just as frustrating as one that is too broad.
A broken door lock and a major property renovation are both rental costs, but they are not necessarily treated the same way for accounting or tax purposes.
Bank feeds have made bookkeeping faster, but they have also created a common misconception: if a transaction has appeared automatically in the software, it must have been recorded correctly.
Owner contributions and draws should also remain clearly identifiable.
This is one area where accounting for real estate investors quickly becomes more involved than everyday income-and-expense bookkeeping. Keeping the source documents with the transaction gives the accountant or tax professional something reliable to work from later.
A healthy overall profit figure does not tell you whether every property is pulling its weight.
Property-level profit and loss reports can show how income and operating costs are developing across individual rentals. A consolidated report then provides the broader portfolio view.
Depending on the operation, investors may also find value in balance sheets, cash flow information, accounts payable or receivable reports, and budget-versus-actual comparisons.
For larger rental portfolios, recorded rent may also need to be compared with property-management records or rent rolls so you can investigate unexplained differences.
No single piece of real estate bookkeeping software suits every investor.
Someone with two rentals may need little more than dependable transaction tracking, bank reconciliation, and clear property reporting. A larger operation may need multi-entity capabilities, document integrations, stronger reporting, and controlled access for bookkeepers or accountants.
Think about what happens if the portfolio doubles. Can the system still separate properties cleanly? Can you produce reports without manipulating spreadsheets every month? Can you find supporting documents when you need them?
Are reconciliations repeatedly pushed into next month? Are expenses being put into whichever category seems closest? Does preparing information for an accountant involve several days of cleanup? Are reports arriving after they would have been useful?
Those are operational problems, regardless of whether the portfolio contains five properties or fifty.
Professional support can handle agreed day-to-day bookkeeping activities while leaving financial oversight and property decisions where they belong—with the investor or management team.
Indian Muneem Chartered Accountant (IMCA) provides End-to-End Bookkeeping Services for businesses that need ongoing support with their financial records.
Need more consistent bookkeeping across your real estate portfolio? Talk to IMCA about outsourced bookkeeping support.
We use cookies and similar technologies to improve your experience, personalise content, analyse website traffic, and understand how visitors interact with our website. Some technologies may help us identify businesses visiting our website and improve our marketing and services. Some cookies are essential for website functionality.